
The US sanctioned the Russia-linked A7 Network and proposed new restrictions to cut its crypto intermediaries off from global markets.
On Oct. 1, the Treasury Department designated A7 as a significant transnational criminal organization, extending blocking sanctions beyond individual companies previously targeted by Washington to the broader payment network. FinCEN simultaneously proposed barring covered financial institutions from transmitting funds involving identified A7 sub-agents.
The measures target a shadow-payment system Treasury says has helped Russian sanctioned entities, Iran’s central bank and Islamic Revolutionary Guard Corps, and other illicit actors move money through companies designed to make restricted transactions resemble ordinary commercial payments.
FinCEN said A7 sub-agents processed more than $17 billion in dollar-denominated transactions between January 2025 and June 2026. Treasury separately said the network claimed in January to be handling more than 2,000 transactions a day worth the equivalent of $91.5 billion, or about 13% of Russia’s 2025 foreign trade.
The designation gives financial firms an immediate compliance obligation where US sanctions jurisdiction applies. Property and interests in property belonging to blocked persons must be frozen and reported to the Office of Foreign Assets Control, including entities owned 50% or more by sanctioned parties.
Washington targets A7’s route into liquid crypto markets
Crypto intermediaries are central to the broader effort because A7 has used its ruble-backed A7A5 token as a bridge into assets with deeper global liquidity.
FinCEN said A7A5 functions as an internal accounting and settlement asset backed by ruble deposits at sanctioned Russian bank PSB. The network has frequently converted the token into more widely accepted digital assets, including Tether’s USDT, which can subsequently be exchanged into fiat currency for international payments.
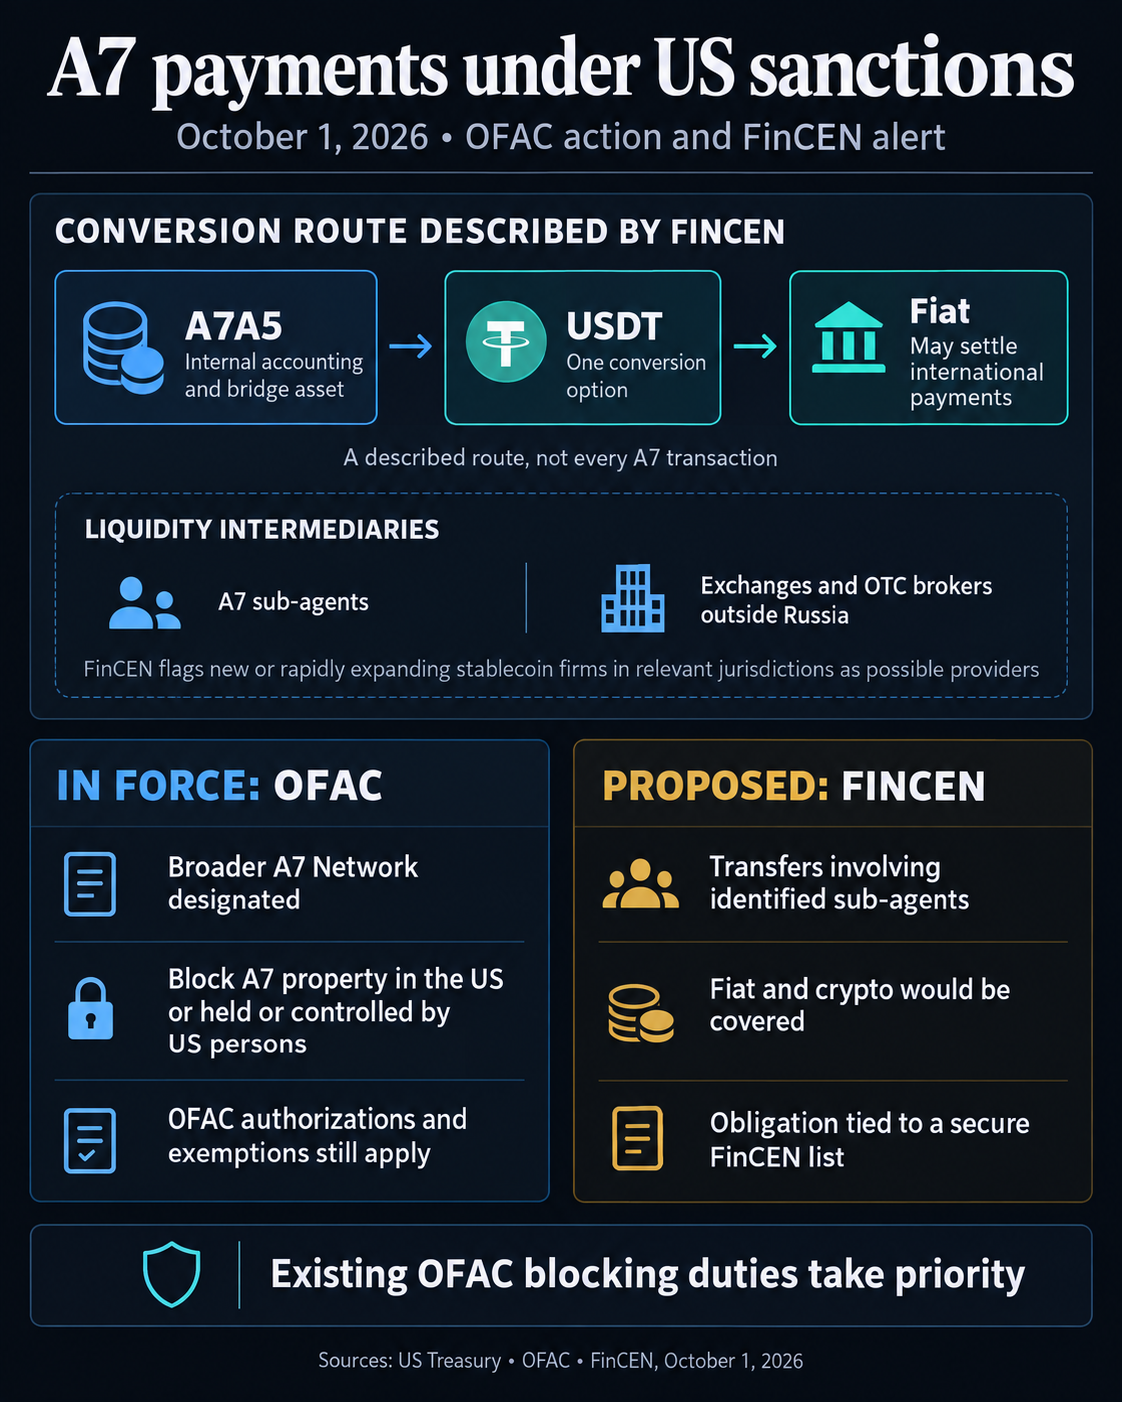
That route puts exchanges, over-the-counter brokers and other liquidity providers outside Russia under greater scrutiny. FinCEN said A7 relies on sub-agents and intermediaries to provide liquidity and move funds while masking the network’s involvement, including through trade documents and payment instructions that make sanctioned activity appear commercially legitimate.
The proposed rule would deepen that pressure by prohibiting covered financial institutions from sending or receiving funds involving A7 sub-agents, including transactions to or from crypto addresses administered on their behalf. Institutions receiving crypto from a listed sub-agent would be expected to block it where other sanctions rules require that outcome or otherwise reject the transfer and deny the intended recipient access.
FinCEN would provide the identities of covered sub-agents through its secure FI-Portal and require institutions to apply risk-based procedures for detecting prohibited transactions. The proposal remains subject to public comment for 30 days after publication in the Federal Register.
That timetable does not delay the sanctions already imposed by OFAC. Crypto exchanges and financial firms with US exposure must now determine whether counterparties, wallet addresses, or payment routes involve A7 property, even as FinCEN works toward a broader transaction ban.
The next pressure point will be the intermediaries supplying the conversion route from A7A5 into USDT and other liquid assets. Once FinCEN circulates its sub-agent list, exchanges and OTC desks will have to decide how aggressively to tighten screening around counterparties that may sit several steps removed from the sanctioned network.