
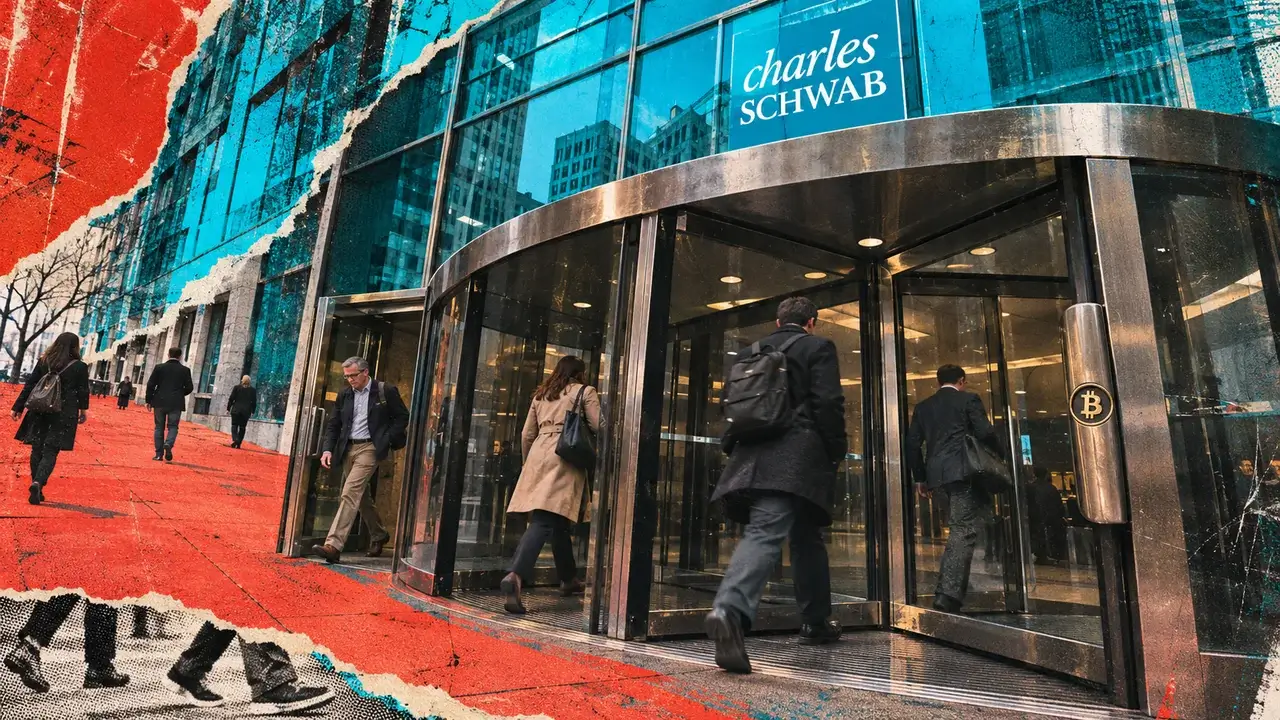
Charles Schwab added Solana, Avalanche and Chainlink to its direct crypto trading service on Nov. 9, giving customers five assets to trade just as the industry’s latest disclosures show fewer active users on some platforms and smaller trades on others.
Coinbase’s monthly transacting users averaged 7.4 million in the third quarter, down from 9.3 million a year earlier.
Banks and brokerages could win existing holders’ business without expanding overall participation, while easier access can redistribute trading revenue even when the overall market is subdued.
Schwab’s token additions follow early access in May and a rollout to all eligible retail clients in October. Its service now offers Bitcoin, Ethereum and the three newly added tokens.
Fidelity’s current trading lineup includes Bitcoin, Ethereum, Fidelity Digital Dollar, Litecoin and Solana through separate Fidelity Crypto accounts. SoFi began a phased consumer rollout on Nov. 11, 2025, bringing crypto into the same app as its other financial services.
These offerings place crypto inside financial relationships customers may already have.
Crypto trading demand is uneven
Coinbase disclosed its user decline in its Oct. 29 filing, attributing its year-over-year decline in monthly transacting users primarily to fewer trading users under current market conditions.
 Coinbase’s quarterly-average monthly transacting users fell
Quarterly-average MTUs: 9.3 million in Q3 2025 and 7.4 million in Q3 2026. Includes passive activity and some non-revenue transfers; this is not a count of unique investors leaving crypto.
 CryptoSlate
The MTU measure includes passive activity and some non-revenue-generating transfers, and the quarterly figure averages monthly measurements.
Coinbase also warns that MTUs can overstate unique consumers. The decline measures activity on Coinbase rather than departures from crypto as a whole.
Gemini’s second-quarter results put exchange trading volume at $4 billion, down from $11 billion a year earlier, while monthly transacting users increased 11% to 580,000.
More users were present, but substantially less money changed hands.
At eToro, preliminary August figures showed the invested amount per crypto trade fell to $97 from $325 a year earlier, a 70% decline. The number of crypto trades fell a much smaller 4%, to 5.3 million.
The platform’s funded accounts rose 18% to 4.36 million, including 110,000 accounts from acquisitions.
Robinhood also reported third-quarter app crypto notional volume of $21 billion, down 48% year over year, and crypto transaction revenue of $120 million, down 55%.
Outside individual platforms, Gallup’s June ownership survey estimated that 9% of US adults held crypto, down from 14% in 2025. Its weighted probability-based sample covered 2,043 adults.
The disclosures show softness across several businesses and in one national ownership measure, but users can hold multiple accounts, ownership differs from trading, and the reporting periods vary.
CoinGecko’s third-quarter report put trading volume on the top 10 centralized spot exchanges at $1.65 trillion, down 14.2% from $1.93 trillion in the second quarter.
CoinGecko’s broader average daily trading-volume measure recovered from $58 billion in July to $95 billion in September. Outstanding positions on the top 10 perpetual-futures exchanges also increased 40.6%, ending the quarter above $100 billion.
Coinbase Institutional’s Nov. 2 analysis then reported that October spot volume fell 16%, while options volume rose 9%.
CoinGecko’s eight-exchange liquidity report, updated Sept. 30, found Bitcoin’s sampled order-book liquidity nearly 50% above its 2025 comparison, while Solana’s fell more than 28.5%.
Trading activity and available market depth are moving in different directions.
The customers financial firms hope to reach
In Schwab’s survey released Oct. 7, six in 10 current crypto investors expected to increase their holdings over the following 12 months.
A poll by the National Cryptocurrency Association and Harris offers another indication of potential demand. In an online survey of 2,017 US adults conducted Sept. 15-16, 42% said crypto access would make them more likely to open a bank account or use it for more of their financial needs.
Even the size of the potential audience is uncertain, since Schwab reported 21% crypto ownership in its unweighted online sample of Americans ages 21-75, compared with Gallup’s 9% estimate from a weighted probability-based survey of adults 18 and older.
Crypto.com’s on-chain-based estimate put worldwide ownership at 774 million in June, up 4.5% from 741 million in December 2025.
A provider can see a large commercial opportunity without expecting an immediate revival in speculative turnover. The addressable holder base and the revenue generated by each active customer are separate questions.
Existing holders moving trading to a bank or brokerage would shift market share, dormant customers returning would increase activity within an existing investor base, and first-time buyers would expand participation.
What growth would mean
An existing holder could move trading from an exchange to a bank or brokerage. The provider gains share without necessarily adding a crypto owner.
A dormant holder could resume trading through the added access. Activity could rise within the existing investor base.
A first-time buyer could enter crypto through a familiar financial platform. This would broaden participation.
Migration shifts share, reactivation restores activity, and first-time adoption expands participation.
The cited announcements do not identify which customer route is driving adoption. No measured customer-flow sizes or forecasts are shown.
Coinbase reported that subscriptions and services accounted for 49% of third-quarter net revenue. Its trading market share increased and paid Coinbase One subscriptions reached a record, showing that weaker activity measures can coexist with growth elsewhere in a platform.
Evidence of a successful expansion would come from funded crypto accounts, unique active traders, assets transferred, and incremental trading volume and revenue. Disclosing whether users are new to crypto or switching providers would distinguish adoption from redistribution.